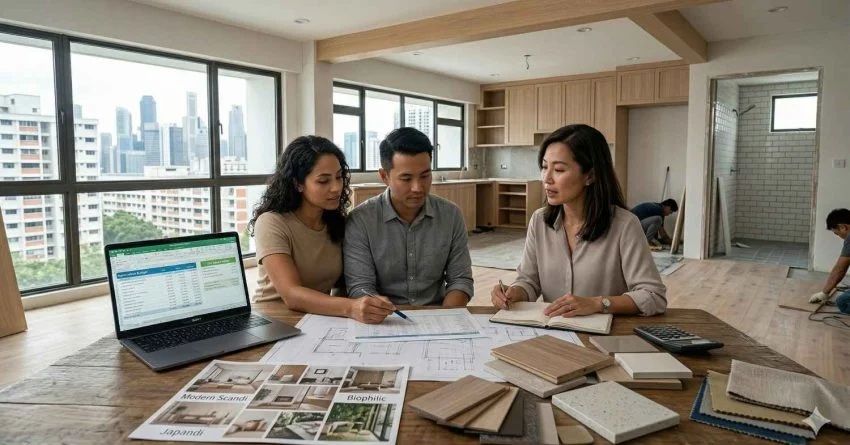
A full renovation of an HDB flat in Singapore typically costs about $40,000 to $77,000 for a BTO flat and about $55,000 to $99,000 for a resale flat, depending on its size. Resale flats cost more because older homes usually need hacking, repairs and replacement work before the new design goes in. Your own bill could be well below or above these ranges, depending on how much you change and the materials you choose.
This guide sets out typical costs by flat type, explains what drives the price, and compares the ways to pay for it, including when a renovation loan makes sense and when it does not.
Typical HDB renovation costs by flat type
The figures below are Qanvast’s estimated renovation costs for HDB flats, based on median costs from 341 BTO and 449 resale renovation projects on its platform, adjusted for 1% to 2% inflation.
Renovation prices move a little each year, mostly because of labour costs. Treat these as a starting point, then get at least three detailed quotations for your own flat.
What drives the cost of an HDB renovation
Resale or new
A BTO flat comes with basic finishes, so most of the budget goes into carpentry, lighting and furnishing. A resale flat often needs old tiles, built-ins and fittings removed first, plus repairs to plumbing, electrical points and windows. That preparation work is why resale renovations cost more for the same flat size.
The biggest cost items
Most of an HDB renovation budget goes to a few areas:
Carpentry: kitchen cabinets, wardrobes, TV consoles and storage. This is usually the single largest item.
Kitchen and bathrooms: tiling, waterproofing, sinks, toilets and fittings.
Flooring: vinyl over existing tiles is cheaper than hacking and retiling.
Electrical and lighting: extra power points, rewiring in older flats, and lighting.
Hacking and masonry: removing walls, floors and old fittings, mostly in resale flats.
Painting, ceiling work and design fees.
Choices that cut the bill
Keep the existing layout. Moving the kitchen or bathrooms adds plumbing and waterproofing costs.
Lay vinyl or overlay flooring instead of hacking out old tiles where the floor is sound.
Limit custom carpentry to the rooms where it matters, and use loose furniture elsewhere.
Compare at least three itemised quotations, line by line.
Buy your own lights, taps and appliances if your contractor allows it.
Before you start: HDB rules to know
Some works need a renovation permit from HDB, and certain works are not allowed at all, such as removing structural walls. Check HDB’s renovation guidelines for your flat before you finalise the design.
Use a contractor listed in HDB’s Directory of Renovation Contractors for works that need a permit.
Keep the quotation, contract and payment schedule in writing. Avoid paying a large share upfront; staged payments tied to completed work protect you if something goes wrong.
How to pay for your renovation
Savings first
Paying in cash avoids interest entirely. If you are buying a resale flat, remember that you may also need cash for the downpayment and any cash over valuation. Our guide to how much cash you need for a resale HDB flat covers those costs. Your CPF savings cannot be used to pay for renovation.
Bank renovation loan
A renovation loan is a loan specifically for renovation works, usually at a lower interest rate than a personal loan.
Banks commonly lend up to six times your monthly income or $30,000, whichever is lower.
The money is usually paid directly to your contractor, based on the quotation, not to you.
It can only be used for renovation works, not furniture or appliances.
Tenures are usually one to five years.
Personal loan
A personal loan pays the cash to you, so you can use it for anything, including furniture and appliances. It is more flexible but usually costs more than a renovation loan.
Renovation loan vs personal loan
If a bank renovation loan covers your works, it is usually the cheaper choice. A personal loan fills gaps that a renovation loan will not cover, such as furniture, or helps when your contractor’s schedule does not suit a bank’s payment process.
Licensed moneylender loan
If you cannot get enough from a bank, a licensed moneylender can lend to cover part of the cost, within the legal cap of six times your monthly income (for annual income of $20,000 or more). Interest is capped at 4% a month, which is higher than bank rates, so it suits smaller top-ups that you can clear quickly, not the whole renovation. See how our renovation loan works and compare the total cost with a bank quote before deciding.
How much should you borrow?
A renovation is a one-off cost, but repayments last for years. Before you borrow:
Set the budget from what you can repay, not from the design. Work out a monthly repayment that fits comfortably alongside your mortgage and other bills.
Keep a 10% to 15% buffer for surprises, especially in resale flats where hidden problems often turn up after hacking.
Think about your home loan. If you are still applying for a mortgage, a renovation loan counts towards your Total Debt Servicing Ratio. Our guide to TDSR in Singapore explains the effect.
Compare the true cost. Look at the effective interest rate and total repayment, not just the monthly instalment. Our guide to EIR vs the advertised rate shows how.
Frequently asked questions
How much does it cost to renovate a 4-room HDB flat?
Based on Qanvast’s estimates, about $50,000 to $60,000 for a 4-room BTO flat and about $70,000 to $81,600 for a 4-room resale flat. A simpler refresh with minimal carpentry can cost much less.
Why is resale renovation more expensive than BTO?
Resale flats usually need old finishes and fittings hacked out, plus repairs to plumbing, wiring and windows, before the new design is installed. That extra labour and preparation work adds to the bill.
Can I use CPF for renovation?
No. CPF savings can help pay for the flat itself, but not for renovation. Renovation is usually paid for with savings, a renovation loan, a personal loan, or a mix of these.
What is the maximum renovation loan in Singapore?
Most banks lend up to six times your monthly income or $30,000, whichever is lower. Joint applications and some banks may allow different limits, so check each bank’s terms.
Is it better to take a renovation loan or a personal loan?
A renovation loan is usually cheaper if it covers what you need. A personal loan is more flexible, since the cash comes to you and can pay for furniture and appliances too, but it usually costs more.
Plan the budget before the design
Decide what you can afford first, get several itemised quotations, and leave a buffer for surprises. If you need to borrow, borrow only the gap between your savings and a realistic budget, and choose the cheapest option that covers it.